An examination of risk, reward, responsibility, and why everyone in the repossession chain deserves consideration.
GUEST EDITORIAL
Every successful business begins with someone willing to take a chance. Someone invests their savings, assumes debt, sacrifices time with family, loses sleep, and accepts the possibility that everything they’ve worked for could disappear.
In the repossession industry, those risks are particularly real.
Agency owners invest substantial capital in trucks, equipment, insurance, facilities, technology, compliance, and personnel. They operate in an environment where liability is significant, regulations are demanding, and a single incident can threaten years of hard work.
Those willing to shoulder such responsibilities deserve to be rewarded.
But as businesses grow, investments are recovered, and financial success becomes increasingly substantial, an interesting question emerges:
At what point does the reward for yesterday’s risk begin to depend more heavily on the sacrifices of those doing the work today?
That question invites a broader examination of whether everyone in the chain receives the consideration, respect, and opportunity necessary to sustain the system they help support.
The Industry Behind the Balance Sheet
The repossession industry occupies a unique position in the financial system. At one end are financial institutions, some managing billions of dollars in assets, answering to investors, shareholders, executives, and regulators.
At the other end are repossession agencies, dispatchers, office personnel, compliance teams, transport drivers, scout car drivers, warehouse personnel, and recovery agents working at all hours to recover collateral.
And somewhere in the middle is the borrower, often experiencing financial difficulty, whose circumstances created the need for recovery in the first place.
Each participant has a different perspective.
Financial institutions have legitimate obligations to protect assets, manage losses, honor agreements, and remain financially sound.
Repossession agency owners must operate profitable businesses while navigating increasing expenses, contractual requirements, and substantial exposure to liability.
Employees need reliable income, safe working conditions, and the opportunity to provide for their families.
Borrowers deserve dignity and fair treatment, even when they can no longer meet their financial obligations.
Shareholders expect returns on their investments.
Technology providers invest in systems, infrastructure, and support that help locate and recover collateral.
Every participant in this chain contributes something, assumes some form of risk, and depends on the others for the system to function.
None of these interests is inherently illegitimate. The challenge lies in balancing them when their priorities compete.
Everyone in the chain deserves consideration—not necessarily identical compensation, but fair recognition of the value, risk, and responsibility they bring to the process.
Who Really Bears the Risk?
Risk is frequently used to justify financial reward, and understandably so. An entrepreneur who builds a business from nothing may spend years working without a predictable paycheck. That commitment deserves recognition.
But risk doesn’t disappear once the business becomes successful. Nor does it belong exclusively to the person whose name appears on the ownership documents.
Consider the recovery agent working alone at 2 a.m.
That individual may face unpredictable confrontations, dangerous environments, physical injury, and the emotional demands of encountering people during difficult moments in their lives.
Consider the scout car driver working 10-hour shifts, five or six days a week.
Spending 50 to 60 hours a week on public roads means constant exposure to traffic hazards, fatigue, unpredictable motorists, and the inherent risks of prolonged driving.
Consider the warehouse personnel responsible for receiving, processing, and releasing repossessed vehicles.
Their work may involve contaminated vehicles, soiled diapers, discarded needles, hazardous materials, and confrontations with distressed or disgruntled debtors retrieving property or redeeming vehicles.
Consider the office staff coordinating recoveries, managing compliance, and communicating with clients and debtors.
They navigate demanding workloads, sensitive interactions, regulatory responsibilities, and the possibility that a single administrative mistake could create significant financial or legal consequences.
Consider the agency owner whose livelihood depends on maintaining contracts with financial institutions that may possess considerably greater negotiating power.
Consider the technology provider that invests in the systems, infrastructure, and support required to make modern recovery operations possible.
And consider the lender, responsible for recovering collateral efficiently while controlling costs and satisfying its own financial obligations.
Each carries risk, although the nature and consequences of those risks differ considerably.
Market forces play a significant role in determining what those risks are worth. Yet market outcomes may also reflect differences in bargaining power rather than differences in contribution alone.
A fuller understanding of risk requires recognizing the different responsibilities and exposures carried by everyone who makes the recovery process possible.
A Question of Scale
Imagine an employee earning $70,000 annually while the chief executive of the organization receives $70 million in total annual compensation.
That is a difference of 1,000 to 1.
Perhaps the executive has created extraordinary value. Perhaps much of that compensation consists of stock awards tied to long-term performance. Perhaps the organization employs thousands of people and operates across multiple continents.
All relevant considerations.
Yet the comparison illustrates how dramatically financial rewards can differ among people contributing to the same organization’s success.
The same issue arises, at different scales, among repossession agency owners, corporate executives, investors, technology providers, and the institutions purchasing recovery services.
Greater responsibility, innovation, and financial exposure can justify substantial differences in compensation. At the same time, extraordinary financial success is rarely achieved without the continuing efforts of many others.
Finding an appropriate balance between rewarding entrepreneurship and recognizing those contributions remains a challenge across nearly every industry.
The objective need not be identical outcomes. Meaningful consideration for every participant is a different principle altogether.
The Economics of Repossession
The repossession industry offers an especially interesting setting for this discussion because financial leverage is often uneven.
A large financial institution may have numerous recovery vendors competing for its business.
An individual agency, however, may depend heavily on contracts with a relatively small number of clients.
When a lender seeks to reduce recovery expenses, the savings may benefit the institution and, ultimately, its investors or customers.
Those savings might come from improved technology, better processes, and greater operational efficiency.
They might also come from lower vendor compensation, reduced margins, increased workloads, or pressure on the people performing the recoveries.
Sometimes both.
An agency owner may feel compelled to accept rates that leave little room for increased employee compensation because declining the work could threaten the company’s survival.
An employee may accept wages or working conditions they consider inadequate because leaving the job could threaten their family’s financial security.
Meanwhile, a financial institution may continue seeking lower costs because its executives are responsible for protecting profitability.
At each level, someone is making a decision influenced by the financial pressures imposed by the level above.
This creates an important distinction between reducing costs and transferring them.
If a financial institution lowers its recovery expenses while agencies struggle to maintain safe, sustainable operations, the apparent savings may come with consequences that are less visible on the institution’s balance sheet.
Conversely, increasing recovery fees does not automatically ensure that additional revenue reaches employees or improves working conditions.
Both sides of the contract have a role in determining whether greater efficiency produces broader benefits.
The relevant consideration is not simply the amount saved, but how those savings are achieved and how they affect the businesses and people supporting the process.
Technology, Opportunity, and the Changing Economics of LPR
Another developing issue within the repossession industry brings these concerns into sharper focus: the evolving role of license plate recognition (LPR) technology and control over the staging of repossession assignments.
For many repossession agencies, investing in LPR technology represented an opportunity to expand their businesses.
Agencies purchased cameras, equipped vehicles, hired drivers, invested in software, and assumed the ongoing costs of operating mobile scanning programs.
The expectation was straightforward: greater investment in locating collateral could generate additional recovery opportunities.
When an agency’s LPR system identifies a vehicle associated with an eligible recovery assignment, staging can help initiate the repossession process. The agency’s investment in technology, personnel, and operating expenses creates the opportunity for a recovery that might otherwise not occur.
However, some industry participants have raised concerns about proposals or arrangements that give other companies greater authority over which agencies may stage assignments, how many assignments they may stage, and the conditions under which staging is permitted.
Depending on how such arrangements are structured, agencies could find themselves with less control over opportunities generated through technology they purchased and operate.
Some models may also introduce staging-related charges, potentially reducing the net revenue available to the agency performing the recovery.
The central issue is the relationship between investment, control, and financial opportunity.
An agency may finance the cameras, employ the drivers, pay for fuel, maintain the vehicles, and assume the operational risks, yet find that another party increasingly determines how its investment can generate revenue.
Restrictions on staging could reduce available recovery opportunities without reducing the agency’s fixed operating expenses. Additional charges could further affect profitability.
Changes introduced after an agency has already committed substantial capital may also create tension between its original business expectations and the economics of continued participation.
There are legitimate reasons for oversight.
Financial institutions and technology providers may seek to prevent duplicate assignments, improve data accuracy, manage compliance, reduce unnecessary costs, or ensure that recoveries are handled by qualified agencies.
Centralized controls could improve efficiency and accountability. Staging fees may also compensate providers for legitimate services. But benefits to one participant do not automatically translate into benefits for everyone else.
A system that lowers administrative costs for lenders or technology providers may simultaneously reduce the opportunities available to agencies that invested in the infrastructure supporting it.
At what point does managing access to an opportunity become controlling the economic value of someone else’s investment?
The answer may depend on transparency, contractual expectations, the availability of alternatives, and whether agencies have a meaningful voice when participation rules change.
It also requires consideration of the interests of everyone involved, not only those with the greatest control over the technology or the contract.
Technology has the potential to make the repossession industry safer, more productive, and more efficient.
The challenge is ensuring that the business arrangements surrounding that technology remain sustainable for those investing in it, operating it, and relying on it for their livelihoods.
The Invisible People Behind Profitability
Financial performance is relatively easy to measure.
Revenue. Expenses. Margins. Shareholder returns. Recovery rates. Average cost per assignment.
The human realities behind those numbers are more difficult to capture.
An employee’s ability to afford an unexpected medical expense.
An agency owner’s concern about meeting payroll or losing a major client.
A recovery agent’s long hours and exposure to unpredictable situations.
A scout car driver’s 50- or 60-hour workweek on public roads.
A warehouse employee’s exposure to hazardous materials, contaminated vehicles, and potentially confrontational situations.
An agency’s uncertainty about recovering its investment in LPR equipment and personnel.
A technology provider’s responsibility to maintain reliable systems while continuing to invest in development, security, and support.
A borrower’s experience during an already difficult financial event.
These realities don’t always appear on an income statement.
Yet they are part of the economic system that produces those statements.
The success of an industry can be evaluated not only by what it earns, but also by the conditions under which those earnings are generated.
That doesn’t mean profitability should be abandoned.
Without profitable lenders, agencies, technology providers, and service providers, the industry cannot function.
But profitability and fair opportunity need not be opposing objectives.
A healthy industry is one in which the success of one participant does not depend unnecessarily on the instability of another.
When Does Success Become Enough?
Financial success is one of the fundamental rewards of entrepreneurship, investment, innovation, and calculated risk.
There should be no expectation that those who build successful businesses must stop pursuing growth or limit their ambitions simply because they have already achieved financial independence.
But as organizations grow, the relationship between financial reward and ongoing contribution becomes more complex.
A business that began with one person’s investment may eventually depend on hundreds or thousands of people whose daily efforts sustain its profitability.
Likewise, a financial institution may generate substantial returns while relying on networks of independent service providers that assume significant operational costs and risks.
Technology companies may develop valuable platforms, but the continued success of those platforms can also depend on the investments and activities of the businesses using them.
Continued financial success provides an opportunity to examine how rewards and responsibilities are distributed among those who make that success possible.
This isn’t necessarily a question of how much someone earns or how wealthy they become.
It’s a question of whether the economic relationships supporting that success remain reasonable, sustainable, and mutually beneficial.
An agency owner deserves to benefit from building a successful company. Employees deserve compensation that recognizes their contributions. Financial institutions deserve returns on their investments. Technology providers deserve to profit from innovation.
These interests do not have to be mutually exclusive.
Long-term success can be measured not simply by how much financial value an organization creates, but also by whether the people and businesses essential to creating that value have a reasonable opportunity to benefit from it.
Everyone in the chain deserves consideration—not because everyone performs the same role, but because every role contributes to the outcome.
A Different Definition of Success
Imagine an industry where financial institutions remain profitable, investors receive reasonable returns, agency owners are rewarded for entrepreneurship, technology providers can sustain innovation, and employees earn enough to support their families with dignity.
Recovery agents would be well trained, appropriately compensated, and not financially pressured to take unnecessary risks.
Scout car drivers would have their long hours, driving exposure, and contributions recognized.
Warehouse personnel would work in safe environments, with appropriate protective equipment, training, and compensation reflecting the hazards and responsibilities of their jobs.
Office personnel would have the resources, training, and support necessary to manage demanding workloads and compliance responsibilities.
Technology providers and agencies would collaborate on LPR programs with clear, predictable staging rules that encourage investment and reward successful recoveries.
Agencies would compete not simply on price, but on professionalism, safety, compliance, employee retention, and long-term performance.
Borrowers would be treated with dignity throughout the recovery process, regardless of their financial circumstances.
Such an approach would involve costs, compromises, and operational challenges. It might also produce benefits that conventional financial measurements do not immediately reveal.
Better compensation could reduce turnover. Experienced employees could improve compliance and operational consistency. Safer working conditions might reduce incidents, litigation, and insurance expenses.
More stable vendor relationships could benefit lenders, while predictable LPR arrangements might encourage continued investment in recovery technology.
None of these outcomes is guaranteed. They are possibilities worth examining.
Improving the lives of people within an industry does not necessarily have to come at the expense of its financial performance.
The Freedom to Walk Away
In theory, an employee who believes compensation is unfair can seek another job.
An agency owner who considers a lender’s rates inadequate can decline the contract.
An agency dissatisfied with the staging rules or fees imposed by an LPR platform can reconsider its participation.
And a financial institution dissatisfied with a vendor can select another provider.
Everyone has a choice.
But those choices may carry vastly different consequences.
An employee living paycheck to paycheck may lack the savings necessary to leave.
An agency supporting dozens of families may be unable to risk losing a contract representing a substantial portion of its revenue.
An agency that has invested heavily in LPR cameras, vehicles, software, and personnel may have limited practical alternatives when staging rules change.
A technology provider may have invested heavily in infrastructure and development before a change in market expectations or contractual arrangements affects its ability to recover those costs.
A large financial institution, meanwhile, may have the resources to withstand a prolonged negotiation or transition between vendors.
These differences don’t automatically establish wrongdoing.
They do, however, illustrate the distinction between having a contractual choice and having the financial freedom to exercise it.
When one party can comfortably walk away and the other cannot afford to, how much of the resulting agreement reflects genuine choice?
The answer matters when evaluating fairness, negotiating power, and the long-term sustainability of business relationships.
It also reinforces the importance of considering every participant when contracts, rates, technology, or operating requirements change.
Perhaps the Question Isn’t Who Deserves Less
Discussions about wealth often become arguments about who should have less. Perhaps that framing overlooks something important.
A more productive discussion might focus on how people and businesses can benefit from the value they collectively create.
That might involve profit sharing, performance incentives, employee ownership, sustainable vendor pricing, transparent technology fees, equitable staging opportunities, or compensation structures recognizing both financial investment and ongoing labor.
Different businesses will require different approaches.
Not every agency can afford generous bonuses. Not every lender can increase recovery fees without consequences. Not every profitable company has excess cash available for distribution.
Technology providers also incur development, infrastructure, security, and compliance costs that must be supported by sustainable business models. And not every disparity in earnings is evidence of exploitation.
But acknowledging those realities does not eliminate the value of examining how rewards are distributed.
Financial success is rarely created by one person acting entirely alone.
It emerges from a combination of capital, leadership, opportunity, employees, customers, vendors, technology, and countless individual contributions.
Recognizing those contributions is both an economic and a philosophical challenge.
The objective is not identical rewards. It is meaningful consideration for those contributing to the outcome.
The Question We Shouldn’t Stop Asking
Perhaps there is no perfect formula for determining how much an entrepreneur, executive, shareholder, agency owner, technology provider, or employee should earn.
Perhaps there never will be.
But an industry can still examine whether its economic relationships reflect the values it claims to uphold. The repossession industry exists because financial agreements sometimes fail. Its professionals encounter the consequences of financial hardship every day.
That experience offers a perspective few other industries possess.
Those who work in repossession understand that financial security can be fragile, circumstances can change quickly, and the difference between stability and crisis is sometimes much smaller than people imagine.
That understanding could inform a more thoughtful approach to compensation, contracting, technology, and fair opportunity. Financial institutions have an interest in the long-term health of the businesses and workers supporting their recovery operations.
Technology providers depend on agencies willing to invest in equipment, vehicles, and personnel that help create the value their platforms deliver.
Agency owners depend on employees whose daily contributions sustain their businesses.
Employees depend on financially healthy organizations capable of providing stable employment and future opportunity.
Borrowers depend on professionals who can carry out difficult responsibilities with competence and dignity.
These relationships are interconnected, even when their economic interests differ.
No single group has all the answers.
But perhaps a civilized and prosperous society is one in which people can work hard, contribute meaningfully, provide for their families, and feel that their efforts are valued—without having to depend on charity or plead for basic financial security.
Success and generosity are not mutually exclusive. Neither are profitability and fairness.
The challenge is determining where those principles meet in practice.
Perhaps the answer begins with recognizing that no one succeeds entirely alone.
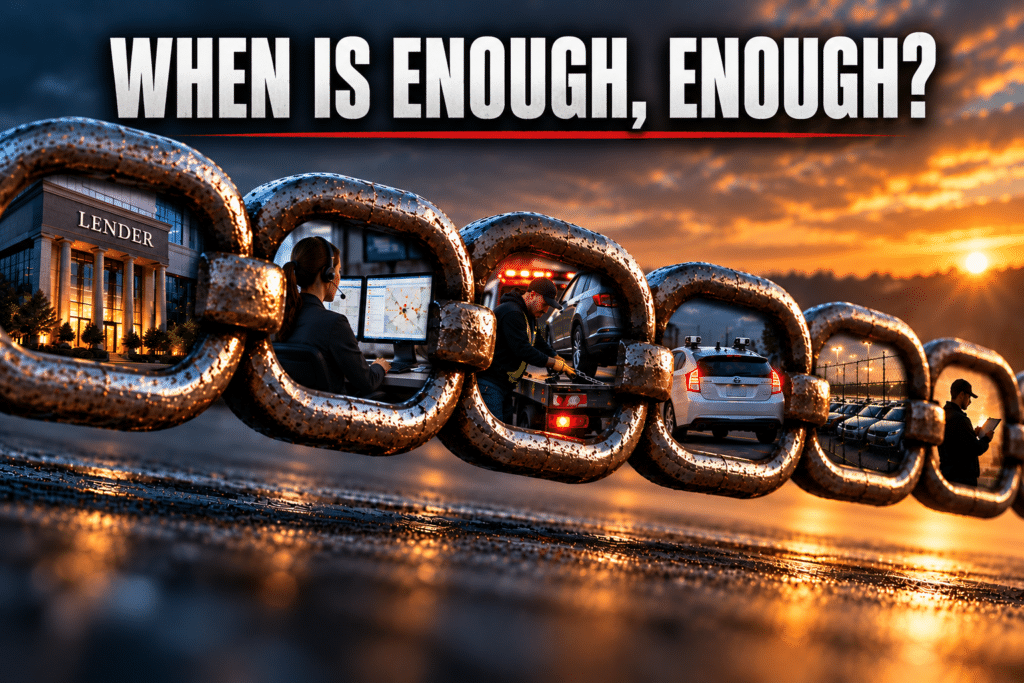
And that brings us back to the question: When is enough, enough?
Maybe the answer isn’t found in the size of someone’s bank account.
Maybe it’s found in how many people are able to prosper alongside them.
WHEN IS ENOUGH, ENOUGH? A Question Worth Asking Across the Repossession Industry – WHEN IS ENOUGH, ENOUGH? A Question Worth Asking Across the Repossession Industry – WHEN IS ENOUGH, ENOUGH? A Question Worth Asking Across the Repossession Industry
Anonymous
WHEN IS ENOUGH, ENOUGH? A Question Worth Asking Across the Repossession Industry – Repossess – Repossession – Repossession Agency – Repossessor – Repossession – Repossession News

More Stories
Three Million Repossessions: A New Measure of America’s Recovery Industry
Why Fight LPR? Join It — But What Happens When the Car Repossesses Itself?
In The Future Will There Be Anyone Left to Recover Vehicles?
The Broken Bond Between Lenders and Agents – Positive Resolution
The Repos That May Never Come
A Repossession Is a Repossession