As camera fleets expand across the repossession industry, are additional cameras producing more recoveries, or just driving up the cost of competing for the same vehicles?
October 28, 2026 — There was a time when adding another license plate recognition (LPR) camera car meant expanding the repossession industry’s ability to locate vehicles that might otherwise have gone unrecovered. More cameras meant more coverage, more sightings, and potentially more recoveries.
There is little question that LPR technology has revolutionized vehicle recovery. Vehicles that once required weeks of skip tracing can now be located through a single camera sighting.
But somewhere along the way, the competition to locate vehicles may have evolved into something else entirely.
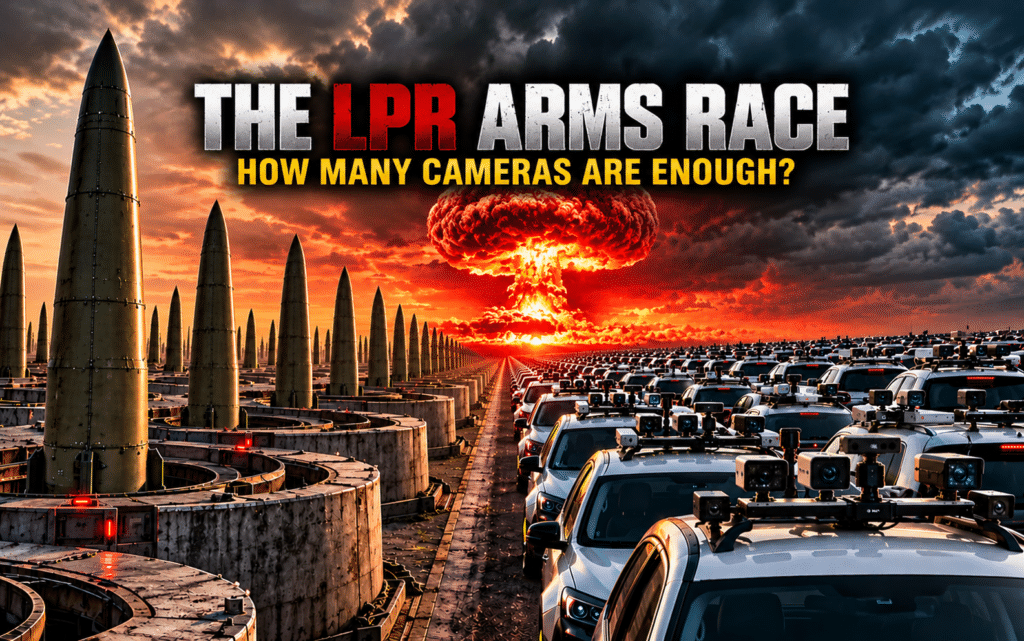
An arms race.
And like the nuclear arms race of the Cold War, the question is becoming less about how much is needed and more about how much the competition has.
Thirty Cameras Versus Fifty
Consider a dilemma recently described by a repossession agency operating approximately 30 LPR camera cars.
His competitor operates 50.
To remain competitive, the agency owner believes he needs to expand his fleet. But he also recognizes that doing so will increase expenses and potentially reduce his profits.
Maintain his existing fleet and risk losing recovery opportunities, or invest in additional cameras that may not generate enough new recoveries to justify their cost.
But what happens when he reaches 50 cameras and his competitor expands to 70?
Does he need 70 now? Eighty? A hundred?
And where does it end?
Neither company has necessarily increased the number of vehicles available for repossession. They may simply be spending more money competing to find the same vehicles first.
The Nuclear Arms Race
During the Cold War, the United States and Soviet Union accumulated enormous nuclear arsenals, each fearful of falling behind the other. The competitive logic was understandable. The collective outcome was enormously expensive and raised the question; how many times over do you need to destroy the planet?
The repossession industry’s expanding LPR fleets may be following a similar economic pattern without the messy Mad Max Armageddon scenario.
No company wants fewer cameras than its competitors. No company wants someone else finding vehicles first. And no company wants to surrender market share because it chose not to expand.
But unlike nuclear weapons sitting in silos, LPR camera cars accumulate operating expenses every day.
Vehicles, drivers, fuel, insurance, maintenance, equipment, software, and data services all cost money. And those expenses continue whether a camera car produces ten recoveries or none.
The economic problem is straightforward: A decision that makes sense for one competitor may become increasingly expensive when everyone makes the same decision.
More Cameras. Same Cars.
The industry has become remarkably sophisticated at measuring LPR activity. Plates scanned. Hits generated. Vehicles spotted.
But how much of that activity represents genuinely new recovery opportunities?
If 20 camera cars cover a metropolitan area, adding another 20 may significantly improve coverage. But what about the next 50? Or the next 100?
At what point does additional coverage begin producing diminishing returns?
A vehicle spotted by five different camera cars is still one vehicle. A recovery assignment located by three competing operators is still one recovery opportunity.
Certainly, repeated sightings provide valuable intelligence, and additional cameras can improve coverage and recovery speed. But more scans don’t necessarily translate into proportionately more completed recoveries.
How many additional completed recoveries does the 100th camera car produce that the first 99 would not have found?
That’s a far more meaningful measure of expansion than the number of cameras operating in a market.
When Competition Becomes Cannibalization
Competition has helped drive the technological progress that transformed vehicle recovery. But it can reach a point where companies are no longer expanding the market. Instead, they are competing more aggressively for the same business.
One operator adds cameras to gain an advantage. Another responds to protect its position. The first expands again.
Costs increase, but the competitive advantage may be temporary.
Meanwhile, traditional repossession agencies still maintain the infrastructure needed to investigate difficult assignments, run addresses, communicate with lenders, handle consumer interactions, and service rural markets where LPR coverage may be limited.
For agencies operating both traditional recovery services and extensive LPR fleets, those expenses can become substantial.
If more resources are directed toward competing for metropolitan LPR recoveries, who will service the difficult assignments and less profitable rural markets?
And what happens when the traditional recovery infrastructure lenders still depend upon becomes economically unsustainable?
Is There Such a Thing as LPR Over saturation?
There have been reports within the industry of LPR networks limiting additional participation in certain markets because of concerns about over saturation.
If accurate, that raises an interesting question.
If network operators themselves recognize that some markets may already have sufficient camera coverage, why are individual agencies still feeling compelled to join or expand?
The answer may be that what benefits an individual competitor doesn’t necessarily benefit the market as a whole.
An agency may need more cameras to maintain its competitive position even when the market doesn’t need more cameras to locate available collateral.
Of course, limiting participation also raises questions about who gets access to the network and who decides when a market has enough coverage.
Neither unlimited expansion nor restricted participation is necessarily the answer.
Who Ultimately Pays?
The costs of expanding LPR fleets don’t disappear. They must be absorbed by the operators, recovered through compensation, offset by other revenue, or passed along somewhere in the recovery process.
LPR data itself has commercial value beyond individual recovery assignments. But for the agencies paying to operate camera cars, the economics must still make sense.
If competition forces agencies to continually expand their fleets while recovery fees remain stagnant, profit margins shrink.
And the consequences may extend beyond the companies operating the cameras.
Lenders and forwarders depend upon a financially healthy network of professional recovery agencies. An industry that becomes increasingly expensive to operate while simultaneously squeezing the profitability of its participants may not be building a sustainable future.
How Many Cameras Are Enough?
Perhaps the most revealing part of the agency owner’s dilemma is that he already recognizes the problem.
He believes he needs more cameras to compete.
He also believes adding those cameras will reduce his profits.
That’s the contradiction at the heart of an arms race.
The investment isn’t necessarily being driven by the expectation of a better return. It may be driven by the fear of falling behind.
None of this suggests that LPR technology has gone too far or that the industry should return to the days of driving endless addresses searching for vehicles that may not have been there for years.
LPR is here to stay, and deservedly so.
Nor does it establish that any particular market has reached over saturation. That would require reliable information about camera density, overlapping coverage, unique recovery opportunities, and the returns generated by additional equipment.
But the industry’s success with LPR shouldn’t prevent it from asking difficult questions about the economics of continued expansion.
Is the industry deploying more cameras because they produce more recoveries, or because our competitors have more cameras than we do?
There is a considerable difference.
During the Cold War, the superpowers eventually recognized that endlessly expanding their arsenals wasn’t necessarily making either side more secure.
The repossession industry may eventually have to confront its own version of that realization.
Because at some point, the question may no longer be who has the most cameras.
It may be who can still afford to operate them.
How many cameras are enough?
The LPR Arms Race: How Many Cameras Are Enough? – The LPR Arms Race: How Many Cameras Are Enough? – The LPR Arms Race: How Many Cameras Are Enough?
Kevin Armstrong
Publisher
The LPR Arms Race: How Many Cameras Are Enough? – License Plate Recognition – LPR – Repossess – Repossession – Repossession Agency – Repossessor – Repossession – Repossession News

More Stories
The Cost of Collecting LPR Data Has Gone Up. Why Hasn’t the Pay?
WHEN IS ENOUGH, ENOUGH? A Question Worth Asking Across the Repossession Industry
Three Million Repossessions: A New Measure of America’s Recovery Industry
Why Fight LPR? Join It — But What Happens When the Car Repossesses Itself?
In The Future Will There Be Anyone Left to Recover Vehicles?
The Broken Bond Between Lenders and Agents – Positive Resolution