With late payments on the rise, a dealership upsell begins to look dangerous.
Lured by low interest rates, low gas prices, and a crop of seductive vehicles that are faster, smarter, and more efficient than ever before, American drivers are increasingly riding in style. Don’t be fooled by the curb appeal, though-those swanky machines are heavily leveraged.
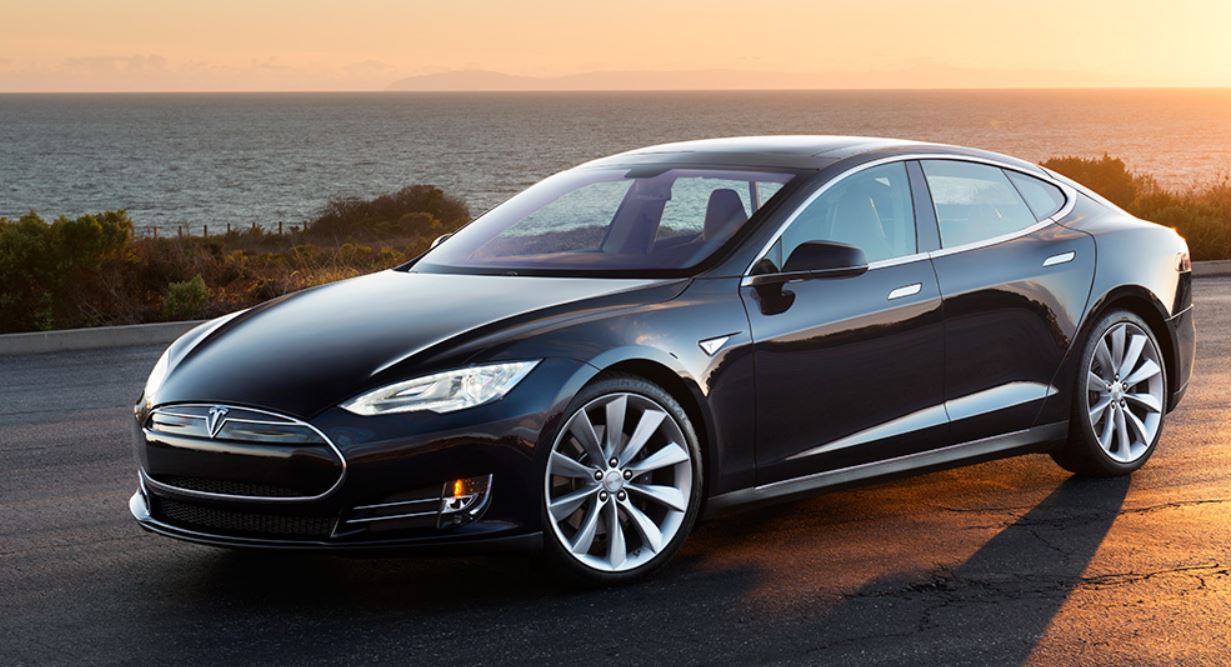
The country’s auto debt hit a record in the fourth quarter of 2016, according to the Federal Reserve Bank of New York, when a rush of year-end car shopping pushed vehicle loans to a dubious peak of $1.16 trillion. The combination of new car smell and new credit woes stretches from Subarus in Maine to Teslas in San Francisco.
Read More!

More Stories
The Cost of Collecting LPR Data Has Gone Up. Why Hasn’t the Pay?
WHEN IS ENOUGH, ENOUGH? A Question Worth Asking Across the Repossession Industry
Three Million Repossessions: A New Measure of America’s Recovery Industry
Why Fight LPR? Join It — But What Happens When the Car Repossesses Itself?
In The Future Will There Be Anyone Left to Recover Vehicles?
The Broken Bond Between Lenders and Agents – Positive Resolution