An Industry Perspective on Uncompensated Efforts, Unrealistic Expectations, and the Threat to the Direct Agent Model
GUEST EDITORIAL
A recent communication distributed by a major national lienholder to its recovery agent network has raised serious concerns about the expectations being placed on direct recovery agents and the growing disconnect between those expectations and the financial realities of the repossession industry.
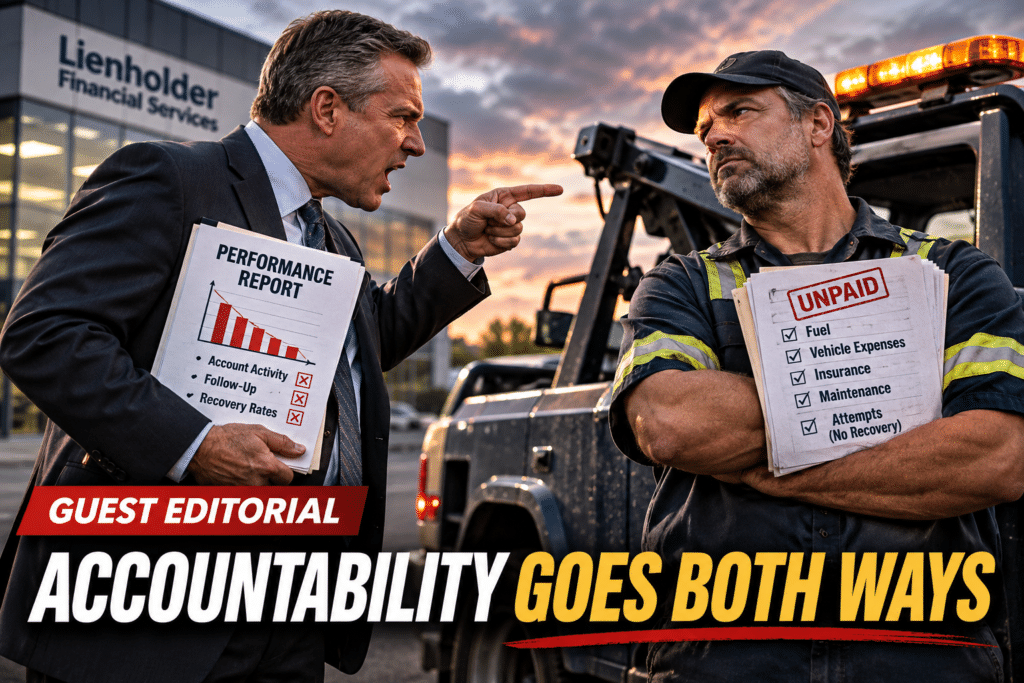
The communication expressed concerns about insufficient account activity, limited follow-up, and declining recovery performance. It further warned that assignments would be shut down with agents who failed to meet performance expectations.
While accountability is necessary in any business relationship, there is another side to this conversation that deserves equal attention.
Who is holding the lienholders accountable for the financial burden they place on recovery agents who are expected to work assignments repeatedly without compensation?
Direct recovery agents commonly operate under contingent-fee arrangements, meaning they are compensated only when a vehicle is successfully recovered. Every unsuccessful attempt, every mile driven, every hour spent investigating an account, and every resource committed to locating collateral comes directly out of the recovery company’s pocket.
And let’s address something the industry rarely discusses openly: fuel expenses are already baked into the repossession fee.
Fuel is not generally an additional expense reimbursed for every unsuccessful attempt. It is hidden within the recovery fee itself, along with equipment maintenance, depreciation, insurance, licensing, technology, labor, and administrative overhead.
That means the recovery agent is expected to absorb all these expenses within a single fee that may never be earned.
The lienholder sees one repossession fee. The agent absorbs the cost of every unsuccessful attempt, including assignments that never produce a recovery.
An unsuccessful recovery does not mean an agent failed to perform the work. It often means the agent performed the work and was never paid for it.
And Now the Threat of Abandoning the Direct Agent Model?
Perhaps the most astonishing part of this ongoing conversation is the suggestion that lienholders may move away from the direct agent model in favor of forwarding companies if recovery performance does not improve.
Really?
The suggestion that adding another layer between the lienholder and the professional actually performing the repossession will somehow improve recovery performance is almost laughable.
Does anyone genuinely believe that inserting a middleman into the process, taking a portion of the recovery fee, and leaving even less compensation for the company performing the actual work will magically produce better results?
Forwarding companies do not eliminate the operational expenses associated with recovery. They do not eliminate fuel costs, insurance premiums, equipment expenses, labor, licensing, or compliance obligations.
The recovery agent still performs the work. The recovery agent still assumes the operational risk. The recovery agent still drives the miles, locates the collateral, and physically secures the vehicle.
The difference is that another entity may now be collecting a portion of the compensation before it ever reaches the company performing the recovery.
If the current direct recovery model is struggling under increasing costs and unrealistic expectations, how exactly is reducing the compensation reaching the actual recovery agent supposed to improve performance?
The predictable concern is that recovery rates could decline even further when the professionals doing the work receive less compensation and have fewer resources available to dedicate to difficult assignments.
Forwarding companies may offer administrative convenience and consolidated reporting, but those services should not be confused with the physical work of recovering collateral. Adding another layer of management does not automatically add another layer of performance.
The industry should be asking whether the forwarding model improves actual recovery outcomes or simply shifts more financial pressure onto the agent at the end of the chain.
Let’s Talk About What Recovery Agents Are Actually Being Sent to Recover
Another issue that deserves serious attention is the condition of assignments before they ever reach the recovery agent.
How many times has the consumer already been contacted?
How many text messages have been sent?
How many phone calls have been made?
And perhaps most importantly, how many times has the consumer effectively been warned that the repossession agent is coming?
The industry continues to see situations where consumers receive repeated communications regarding delinquency, potential repossession, and the anticipated arrival of a recovery agent.
Then the assignment is forwarded to the recovery company with the expectation that the vehicle and consumer will be sitting at the provided address, ready and waiting for a convenient pickup.
Seriously? How much more difficult can we make the recovery process before blaming the recovery agent for the outcome?
Repeated communications may serve legitimate servicing, compliance, and consumer-notification purposes. But lienholders must recognize that these communications can also affect the likelihood of locating collateral.
If a consumer has been repeatedly contacted and alerted to the possibility of repossession, it should come as no surprise that the vehicle may no longer be sitting in the driveway when the recovery agent arrives.
Yet the agent is still expected to produce results as though the assignment were fresh, the location information were accurate, and the collateral were readily available.
And when the vehicle cannot be located?
The agent is questioned about performance.
The agent is asked for additional updates.
The agent is expected to make more attempts. And the agent still receives no compensation for the unsuccessful work.
At some point, lienholders must acknowledge that their own processes, communications, and assignment practices can influence recovery outcomes.
You cannot repeatedly alert consumers to impending recovery activity, assign the account to an agent, and then act surprised when the vehicle is not available.
More Demands, More Expenses, Less Compensation
Recovery companies are being asked to do more than ever before.
More documentation. More technology. More compliance. More reporting. More attempts. More communication. More accountability.
All while operating expenses continue to increase and compensation structures often remain unchanged.
Recovery companies must maintain expensive equipment, qualified employees, insurance coverage, technology platforms, secure storage facilities, and compliance programs.
These are not optional expenses.
Yet the expectation remains that agents should continue investing unlimited resources into assignments that may never produce a dollar of revenue.
Recovery companies are businesses, not volunteer organizations.
The financial risk of unsuccessful assignments should not automatically fall entirely on the recovery agent while the lienholder retains the ability to demand repeated efforts without additional compensation.
Accountability Must Work Both Ways
Let’s be clear: this is not an argument against accountability.
Recovery agents who accept assignments should work them responsibly, document their activity, communicate effectively, and comply with applicable laws and professional standards.
Agents who consistently fail to perform should absolutely be held accountable. But accountability must be measured fairly.
A vehicle that cannot be located is not necessarily evidence of an agent who failed to work the account.
A recovery rate does not tell the entire story.
And the number of attempts recorded does not necessarily reflect the quality of the assignment, the accuracy of the information provided, or the circumstances surrounding the collateral.
Lienholders should also be evaluating their own performance.
Are assignments being provided with accurate and current information?
Are consumers being repeatedly contacted or alerted before recovery efforts begin?
Are recovery expectations realistic?
Are direct agents being compensated fairly for the work they are expected to perform?
And are forwarding arrangements genuinely improving recovery results, or simply reducing the compensation available to the companies performing the actual work?
If lienholders want accountability from their recovery partners, they should be willing to accept accountability for the conditions under which those partners are expected to perform.
The Direct Agent Model Is Not the Problem
The direct agent model provides a relationship between the lienholder and the licensed recovery company actually responsible for performing the work.
It allows for direct communication, operational accountability, and transparency regarding recovery activity.
Replacing that relationship with an additional intermediary does not automatically resolve poor assignment quality, difficult-to-locate collateral, consumer avoidance, or inadequate compensation.
In fact, when forwarding arrangements reduce the amount ultimately paid to the recovery company, they can make the economics of recovery even more challenging.
The industry should be focused on strengthening direct agent partnerships, not threatening to replace them whenever performance metrics fail to meet expectations.
You cannot fix an undercompensated recovery network by creating a model that potentially compensates the actual recovery agent even less.
The Question Nobody Seems to Want to Answer
How much uncompensated work should a recovery company reasonably be expected to perform?
How many times should an agent drive to an address before the lienholder recognizes the expense involved?
How many unsuccessful attempts should be required when the information provided is outdated or the consumer has already been repeatedly warned?
And how does adding a forwarding company that retains a portion of the recovery fee improve the financial ability of the actual recovery agent to perform?
These are legitimate business questions, and the industry deserves legitimate answers.
The repossession industry needs strong, financially stable, compliant direct recovery agents. Lienholders need dependable recovery partners.
But those partnerships cannot remain healthy when one side dictates increasingly demanding performance expectations while the other absorbs nearly all the expense and risk of unsuccessful assignments.
The direct agent model does not need more threats. It needs meaningful partnerships, realistic expectations, and fair compensation.
Perhaps it is time for lienholders to stop asking only why their recovery agents are not producing more results and start examining whether their own practices are making those results increasingly difficult to achieve.
Because at the end of the day, the recovery agent cannot recover a vehicle simply because a spreadsheet, performance report, or corporate directive says it should be there.
Performance matters. Effort has value. Compensation matters. And accountability should never be one-sided.
Accountability Goes Both Ways: Is the Direct Recovery Agent Becoming the Industry’s Scapegoat? – Accountability Goes Both Ways: Is the Direct Recovery Agent Becoming the Industry’s Scapegoat? – Accountability Goes Both Ways: Is the Direct Recovery Agent Becoming the Industry’s Scapegoat?
Submitted anonymously by a concerned member of the collateral recovery industry.
Accountability Goes Both Ways: Is the Direct Recovery Agent Becoming the Industry’s Scapegoat? – Forwarder – Fuel Costs – Gas Prices – Repossess – Repossession – Repossession Agency – Repossessor – Repossession – Repossession News

More Stories
The Industry of Silence: When Speaking Up Could Cost You Everything
The Self-Inflicted Wound: Repo-Averse Lenders and the Decline in Recovery Rates
Without Change is the Risk worth the Reward?
The Repossession Industry Is Eating Its Own
Twelve Years, Seventy-Five Dollars
The LPR Arms Race: How Many Cameras Are Enough?