As charge-offs approach 2019 peaks, lenders expand their subprime portfolios despite mounting credit risks.
November 2, 2026 — Subprime auto lending is sending some contradictory signals. While credit losses remain elevated and charge-offs approach levels not seen in seven years, lenders continue expanding their exposure to higher-risk borrowers.
Rather than retreating from subprime lending, companies including OneMain Financial and Credit Acceptance Corporation are reporting substantial growth, even as credit-loss provisions climb and collection forecasts weaken.
It raises an interesting question: Are lenders chasing higher yields to offset mounting losses, or attempting to grow their portfolios faster than their delinquencies?
Recent third-quarter earnings reports suggest both possibilities deserve attention.
Credit Acceptance: Growth Surges as Collection Forecasts Fall
Credit Acceptance’s October 29 earnings release provides perhaps the clearest example of the tension between subprime growth and weakening loan performance.
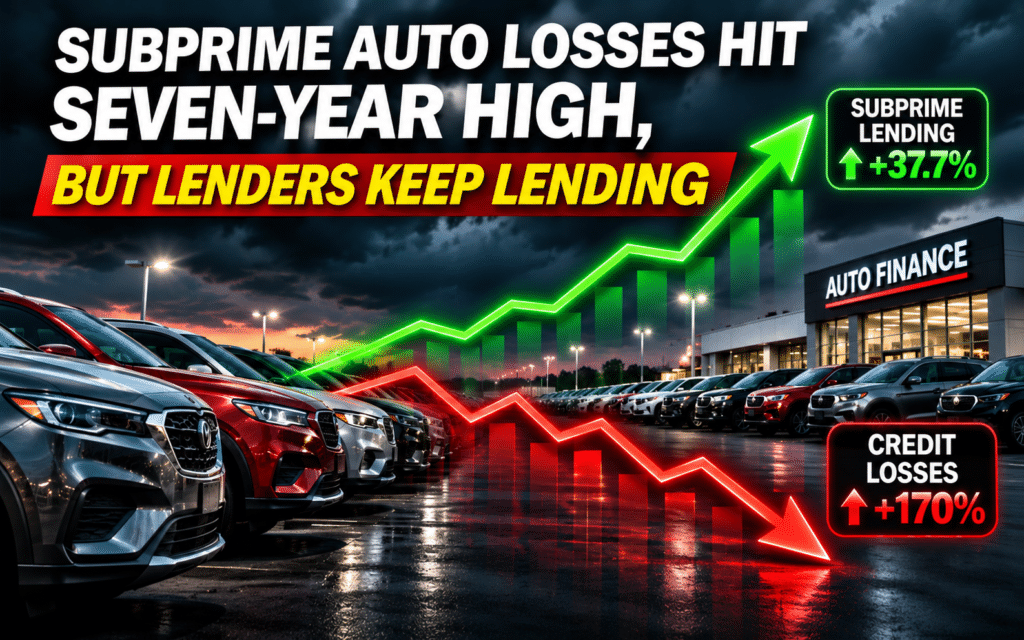
The company’s loan assignments increased 37.7% to 110,010 vehicles, while dollar volume surged 51% to $1.4 billion. Its active dealer network expanded 18.8% to a record 12,093 dealers.
But while new business was booming, expectations for collections on existing loans were moving in the opposite direction.
Credit Acceptance reduced its forecasted portfolio cash flows by $291.2 million, or 2.5%, compared with a $58.6 million reduction during the same quarter last year.
Its provision for credit losses climbed 170% to $410.9 million, up from $152 million a year earlier.
The company acknowledged that loans originated in recent years had consistently underperformed collection expectations, particularly among borrowers in its lower credit-scorecard bands. A revised forecasting methodology accounted for much of the latest adjustment.
Credit Acceptance reported a $56.6 million GAAP net loss, compared with $108.2 million in net income a year earlier. However, adjusted net income increased 14.9%, indicating that the accounting impact of revised collection forecasts was a major factor in the reported loss.
Nevertheless, the contrast is striking: Credit Acceptance is financing substantially more vehicles while reducing expectations for collecting on loans already in its portfolio.
OneMain: Expanding While Absorbing Higher Credit Costs
OneMain Financial’s October 30 earnings report reveals a similar trend.
The company’s auto finance receivables increased approximately 16% year over year to $3.2 billion, while total managed receivables reached $28.1 billion.
Meanwhile, quarterly provisions for credit losses increased to $615 million, compared with $488 million a year earlier.
That provision represented approximately 41% of OneMain’s $1.49 billion in quarterly interest income.
Although provisions include reserves for anticipated future losses and are not equivalent to actual charge-offs, the figures illustrate how much of a lender’s interest income can be consumed by the cost of credit.
OneMain’s credit performance was mixed, with its net charge-off ratio improving from the previous quarter. Management also attributed some of the higher provisioning to portfolio growth rather than deteriorating loan performance alone.
Still, the company is expanding its lending business while carrying substantial credit-loss expenses.
Can Growth Make Delinquency Look Better?
One overlooked consequence of rapid portfolio expansion is its effect on delinquency ratios.
Consider a lender with 100,000 outstanding loans and 5,000 accounts at least 60 days delinquent. Its delinquency rate is 5%.
If that lender expands to 125,000 loans while delinquent accounts increase to 5,500, the delinquency rate falls to 4.4%.
The lender now has more delinquent borrowers, but a lower reported delinquency ratio.
That doesn’t suggest deliberate manipulation. It simply demonstrates how portfolio growth can improve percentages without necessarily reducing the number of troubled accounts.
Newly originated loans also need time to season before their eventual credit performance becomes apparent.
What About Loan Modifications?
Another missing piece is the growing importance of payment extensions, deferments, and loan modifications.
These arrangements can help borrowers avoid default and allow lenders to preserve payment streams rather than immediately pursuing repossession.
But they can also delay the appearance of more serious delinquency problems.
Unfortunately, consistent industry-wide comparisons of current auto-loan extension and modification rates against previous years remain difficult to obtain.
Without knowing how many borrowers are receiving extensions, how often those extensions are repeated, and how many ultimately default, declining delinquency ratios may not tell the entire story.
Are Higher Yields Worth the Losses?
Subprime lending has always depended on higher interest rates compensating lenders for greater credit risk.
But higher yields mean little if increasing credit losses consume the additional income.
Interest revenue must cover funding costs, credit losses, servicing, collections, and operating expenses before producing a profit.
For some lenders, expansion may represent a calculated opportunity to capture profitable business. For others, additional loan production may help offset earnings pressure from older, under-performing portfolios.
The danger comes when continued growth becomes increasingly important to maintaining earnings while earlier originations fail to perform as expected.
Credit Acceptance’s latest collection forecast reductions make that possibility particularly relevant.
What Does This Mean for Repossessions?
For the recovery industry, the consequences of today’s lending expansion may not appear immediately.
Loans originated in 2026 could take months or years to progress through delinquency, extensions, default, and eventual repossession.
If today’s expanding subprime portfolios eventually experience the same repayment difficulties as earlier originations, the industry could face another increase in recovery assignments during 2027 and 2028.
However, improved underwriting, more effective collections, or successful loan modifications could moderate that outcome.
The larger question is whether lenders are genuinely improving their ability to manage subprime risk or simply becoming more willing to accept it.
There is nothing inherently irresponsible about expanding subprime lending. But when loan production accelerates while credit-loss provisions rise and collection forecasts weaken, it becomes increasingly important to distinguish profitable growth from growing exposure.
And if lenders are counting on continued portfolio expansion to stay ahead of their credit losses, what happens when that growth eventually slows?
Subprime Auto Losses Hit Seven-Year High, But Lenders Keep Lending – Subprime Auto Losses Hit Seven-Year High, But Lenders Keep Lending – Subprime Auto Losses Hit Seven-Year High, But Lenders Keep Lending
Subprime Auto Losses Hit Seven-Year High, But Lenders Keep Lending – Repossess – Repossession – Repossession Agency – Repossessor – Repossession – Repossession News – Lending – Auto Loan – Modifications – Subprime Auto Loans – Subprime Auto Loans – Delinquency

More Stories
Philadelphia Expands Electronic Repo Reporting to Eight Police Districts
Repo Agent Hospitalized After Being Pinned by Tesla
MAUCK RECOVERY MOVES FORWARD
Arrested Indiana Repossessor’s Family Calls Kidnapping Allegations a Misunderstanding
Repo Yard Ram Raid
Indiana Repossessor Arrested in Alleged Attempted Kidnapping of Teenage Girl